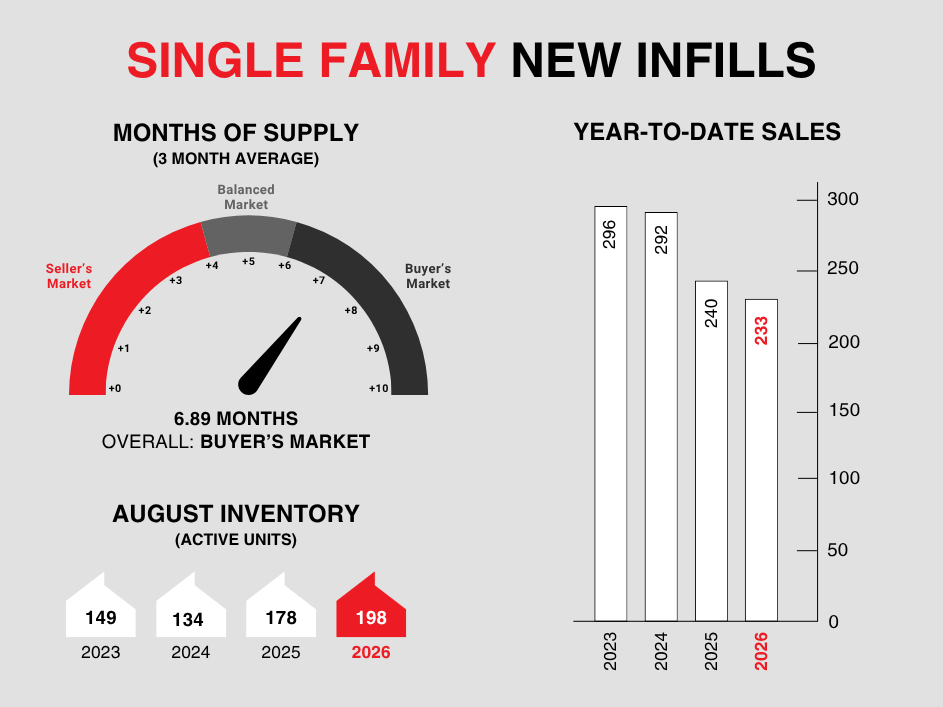
Single family new infill sales hold steady while inventory levels trend upwards.
Single-family new infills posted 22 sales during the month of August, nearly on par with the 23 sales posted in July, as well as the 22 sales posted in August of last year.
Single-family new infill inventory increased through August, both month over month and year over year. 198 active listings were recorded for sale in August, compared to 178 active listings last month and 178 active listing recorded at this time last year.
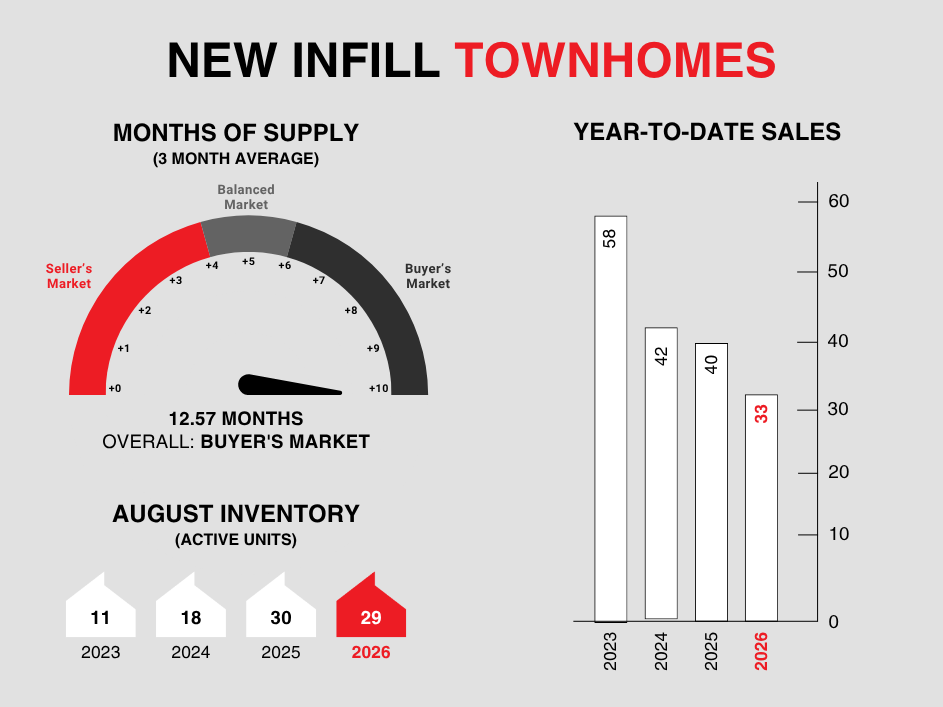
New infill townhomes posted 3 sales in August, up from 1 sale recorded last month but on-par with the 3 sales recorded in August of last year.
New infill townhome inventory remains unchanged, with 29 active listings for sale, slightly down from 30 active listings for sale at this time last year.
Sales activity for both single-family and townhome new infills is expected to remain relatively steady over the coming months unlike the overall market which has a history of trending downwards as we move towards cooler weather and the end of the calendar year.
CALGARY MARKET UPDATE (CREB)
Calgary, Alberta, September 1, 2026 – Consistent with trends throughout most of 2026, both sales activity and the number of new listings coming onto the market have continued to trend down compared with 2025 levels. In August, sales in Calgary were 1,660 units, down 16% compared with last year, while new listings fell by nearly 10% to 3,141 units.
The pullback in sales has not occurred across all price ranges, as homes priced over $1,000,000 have recorded gains over last year. These gains have mostly been driven by detached and semi-detached homes and are also consistent with where most of the supply growth has occurred.
“While sales growth in the upper end of the market was possible thanks to improved supply choice, it also reflects longer-term confidence in our market, as some buyers are not shying away from taking advantage of the available supply,” said Ann-Marie Lurie, Chief Economist at the Calgary Real Estate Board (CREB®). “Meanwhile, we have not seen the same pickup in activity in the lower price ranges, as favourable rental conditions are slowing the transition to ownership.”
Inventory levels in August eased compared with the previous month and the same period last year, at 6,509 units. However, given the pullback in sales, the months of supply pushed up to nearly four months. Also consistent with trends throughout this year, conditions vary significantly by property type, with nearly six months of supply for apartment-style homes compared with over three months of supply for lower-density detached homes.
The relatively balanced conditions in the detached and semi-detached sector have prevented any significant shifts in prices compared with the steady price declines occurring in the oversupplied higher-density segments of the market. As of August, the total residential benchmark price was $569,800, similar to the previous month and 1% lower than 2025 levels.