Single-family new infill sales ease in October as inventory levels continue to climb, while new infill townhomes post improved sales activity.
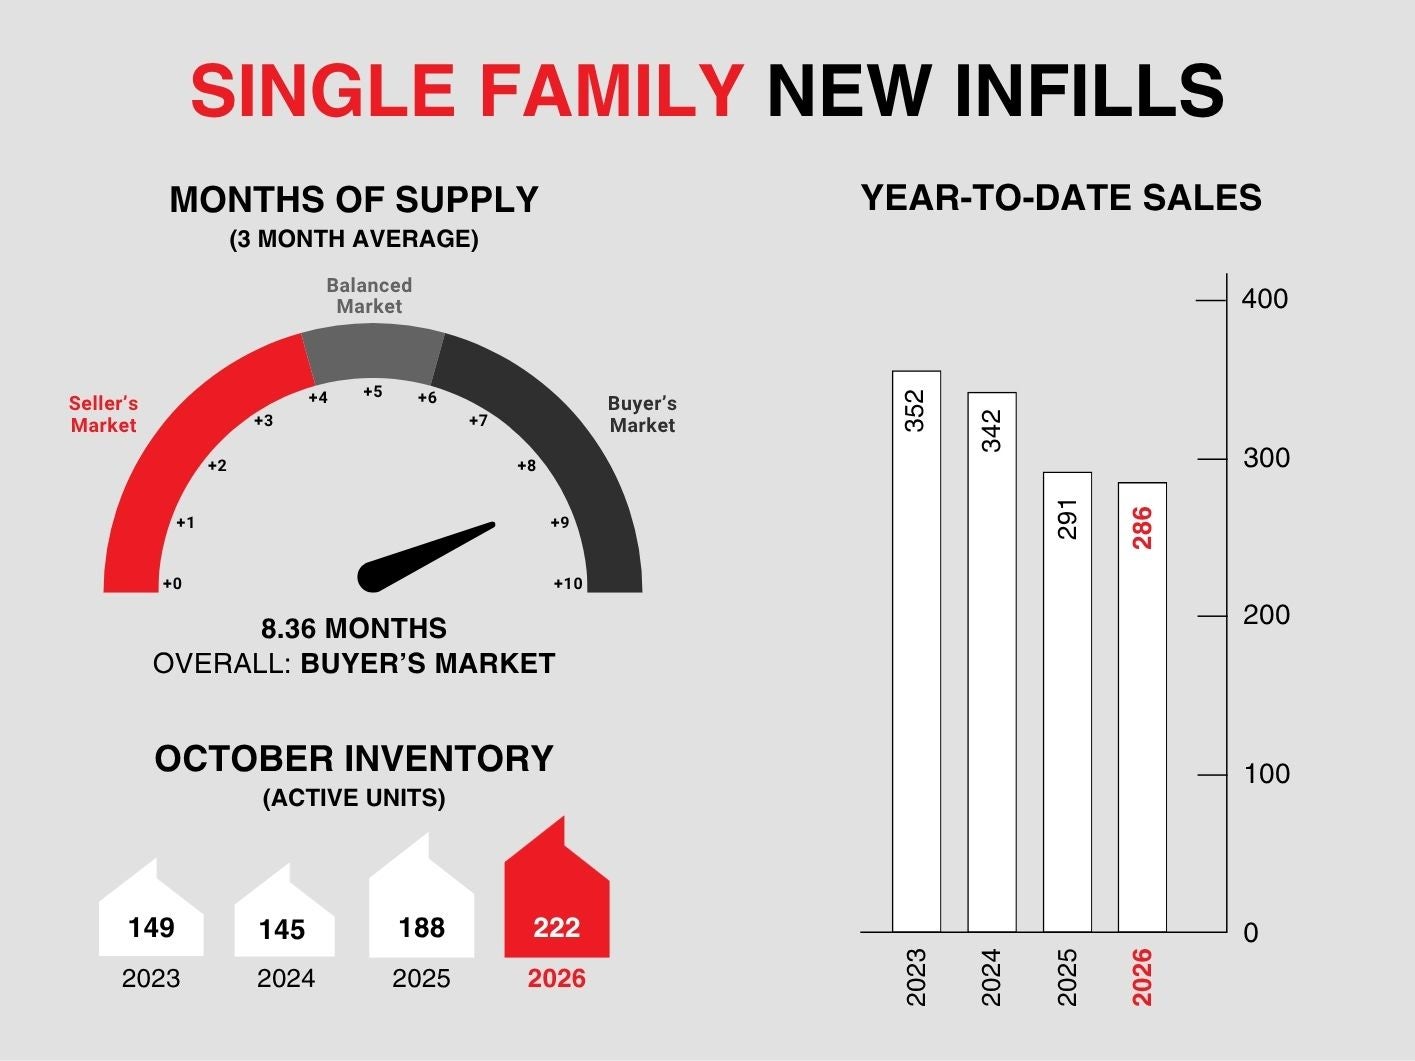
Single-family new infills posted 24 sales during the month of October, down from the 29 sales recorded last month and down considerably from the 37 sales recorded in October of last year. Year to date, single-family new infill sales total 286, down 1.7% from last year.
Single-family new infill inventory increased further in October, up to 222 active listings for sale, compared to 207 active listings recorded last month and 188 active listings recorded at this time last year.
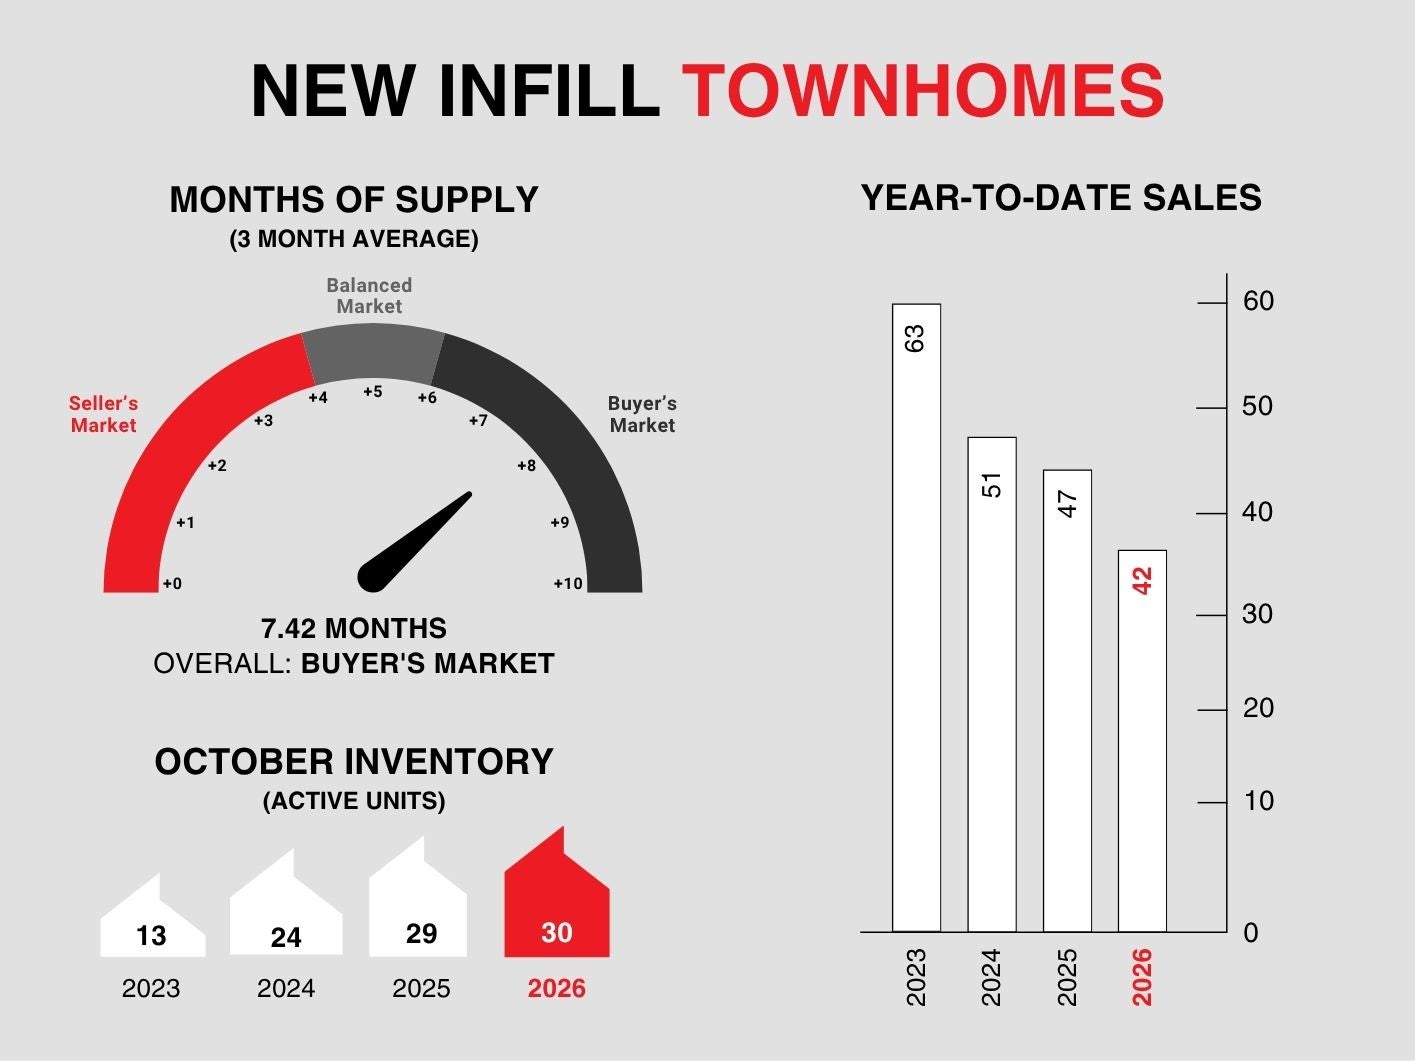
New infill townhomes posted 6 sales during the month of October, up from the 3 sales recorded last month and also up from the 3 sales recorded in October of last year. Year to date, new infill townhome sales total 42, down 10.6% from last year.
New infill townhome inventory remains steady, with 30 active listings for sale, unchanged from last month and slightly up from the 29 active listings recorded at this time last year.
With single-family new infill inventory continuing to rise and sales activity easing, buyers are finding themselves with more options as we head towards the quieter winter months. The Bank of Canada's recent 25 basis point interest rate increase, bringing the overnight rate to 2.5%, may place further pressure on affordability and buyer confidence. We expect sales activity to moderate over the coming months, with competitive pricing becoming increasingly important for sellers looking to secure a sale before year-end.
CALGARY MARKET UPDATE (CREB)
Supply levels ease as we move into winter
Calgary, Alberta, Nov. 2, 2026 – October sales slowed to 1,592 units, contributing to a year-to-date decline of nearly 11%. While sales have slowed this year, much of the decline was driven by steep pullbacks in resale apartment condominiums and row-style units. Although sales have fallen across all property types, we have seen a pickup in sales of homes that are priced above $1.5 million, which account for less than 4% of all sales activity.
The overall pullback in sales was met with further declines in new listings, causing inventories to trend down in October. In line with typical seasonal behaviour, inventories slowed from September, leaving inventories nearly 5% lower than October 2025 levels. With 6,173 units in inventory and 1,592 sales, the months of supply remained just below four months. The elevated months of supply is mostly due to shifts in the higher-density apartment and row sectors of the market, which both tend to favour the buyer. Meanwhile, detached and semi-detached markets remain relatively balanced.
“Supply choice in the new, rental and resale markets has taken much of the pressure off prices this year. However, supply choice can vary significantly within the market, resulting in divergent impacts on prices,” said Ann-Marie Lurie, Chief Economist at the Calgary Real Estate Board (CREB®). “Much of the downward pressure on prices is occurring in the oversupplied higher-density segments of the market, while detached and semi-detached prices have remained more stable. Even within the detached market, we see variation as the City Centre and West districts continue to report price gains over 2025, while prices have declined by more than 6% in the North East district.”
In line with seasonal expectations, October’s benchmark price eased compared with September, and remained similar to last year’s levels. While much of the price adjustment in the market occurred in the second half of 2025, we did not see the same seasonal lift in prices in spring 2026, leaving year-to-date prices nearly 3% lower than October 2025. Year-to-date benchmark prices ranged from stable in the semi-detached sector to a decline of nearly 9% in the apartment condominium sector.